401(k) Direct Rollover: When to Move It and When Not To
Direct vs indirect 401(k) rollover: the 20% withholding trap, the 60-day rule, and when leaving money in the plan keeps the Rule of 55 and lower costs.
When you leave a job, the 401(k) can stay where it is, move to a new employer's plan, roll into an IRA, or be cashed out. If you move it, ask for a direct rollover: the plan pays the new plan or IRA, nothing is withheld, and no 60-day deadline applies.1 Paid to you instead, the plan must withhold 20% of the taxable amount, and you have 60 days to put the full amount back.2 Moving is not automatically the right call: if you plan to draw on this money between 55 and 59½, rolling it into an IRA can cost you the Rule of 55.
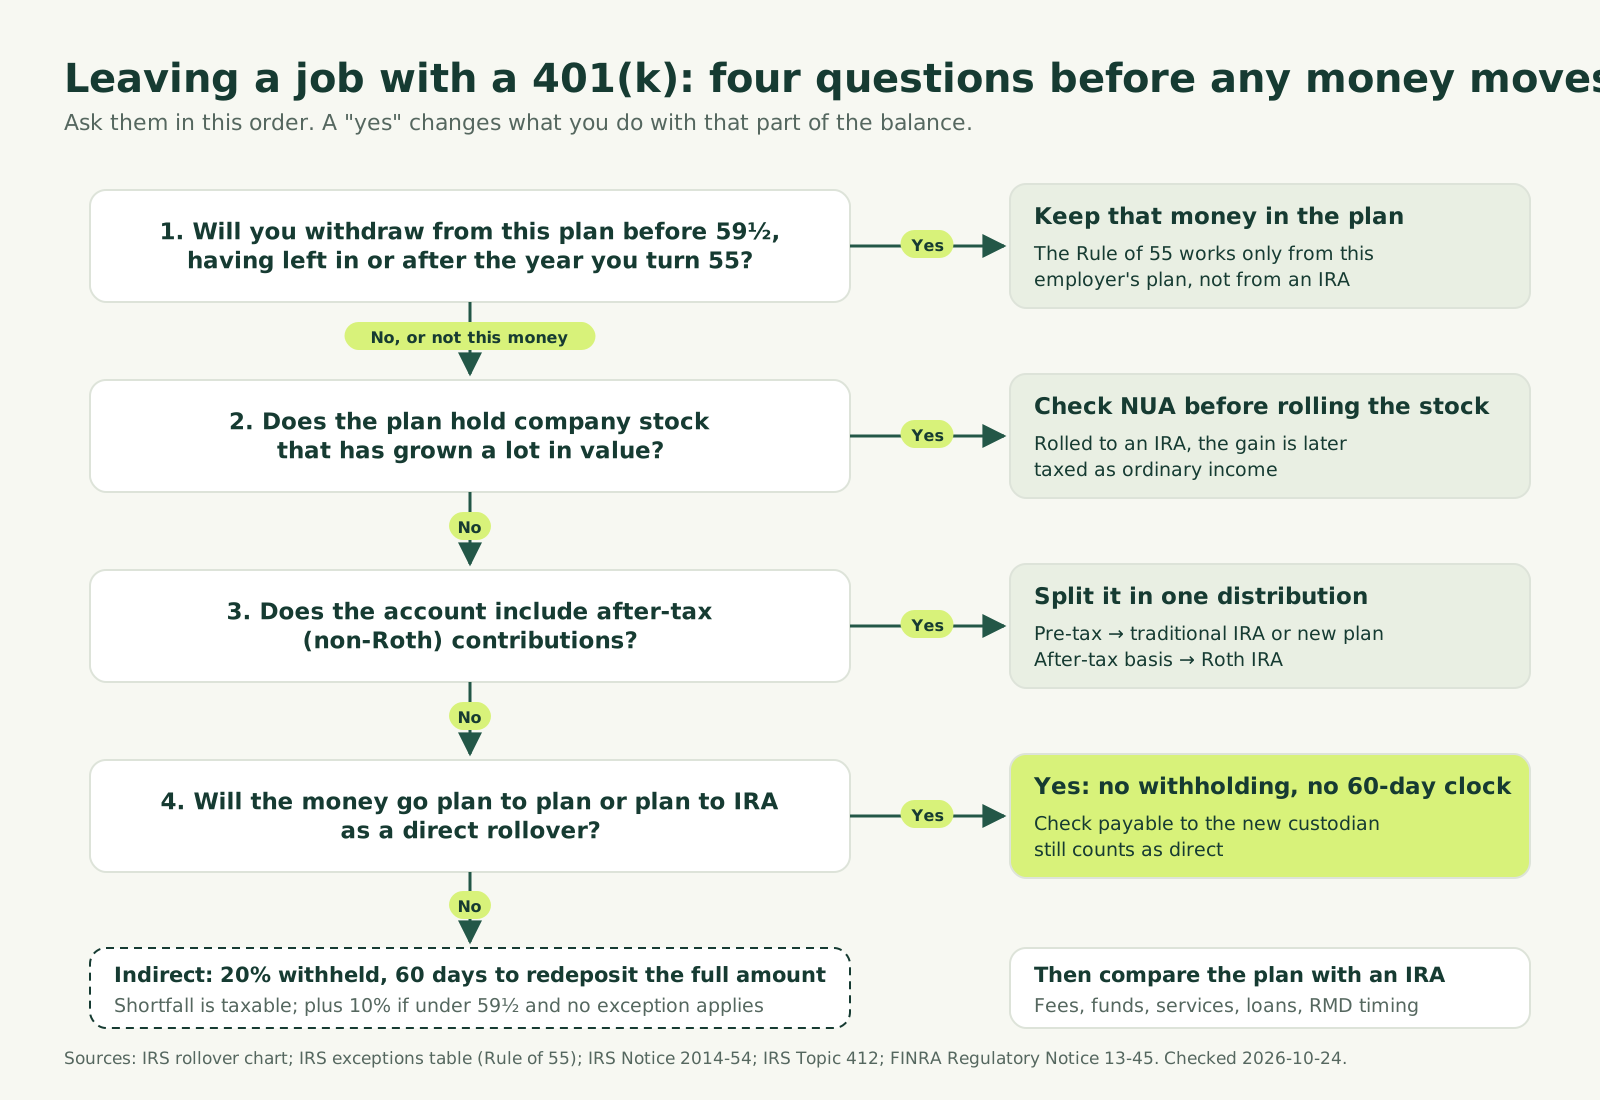
The order of questions matters more than the paperwork. Run through them before you call anyone.
The four options and what each one keeps
FINRA's notice on rollovers lists the same four options for someone leaving an employer, and notes you can combine them.10 Splitting is common: one part stays in the plan, another goes to an IRA.
| Option | What you keep | What changes |
|---|---|---|
| Leave it in the old plan (if the plan allows) | The plan's funds and fees, the Rule of 55 for that plan | No new contributions; you deal with a former employer's administrator10 |
| Roll into the new employer's plan | Tax deferral, one account, plan features such as loans if the plan offers them | The new plan does not have to accept rollovers; ask what it takes1 |
| Roll into an IRA | Tax deferral, often a wider choice of investments10 | The Rule of 55 no longer applies to that money; IRA fees replace plan fees6 |
| Cash out | Nothing stays sheltered | The taxable amount is income this year, plus the 10% additional tax if you are under 59½ and no exception applies2 |
Doing nothing is also a choice with rules. A plan can move or pay out a small account without your consent, and before any eligible distribution it must give you a written explanation of your options, including a direct rollover.1
Direct or indirect: what the check is made out to decides it
A direct rollover is a payment from the plan to the receiving plan or IRA. The administrator may still mail you a paper check, and that often worries people. What matters is the payee. A check made payable to the new account (often written "FBO" your name) is a direct rollover, and no tax is withheld from it.1 You are only the courier. Send it with tracking.
An indirect rollover, also called a 60-day rollover, is a distribution paid to you. From a 401(k), the plan must withhold 20% of the taxable part, even if you say you will roll it over.1 To keep the whole distribution tax-free, you deposit the full pre-withholding amount within 60 days, using other money to cover the part that went to the IRS.2
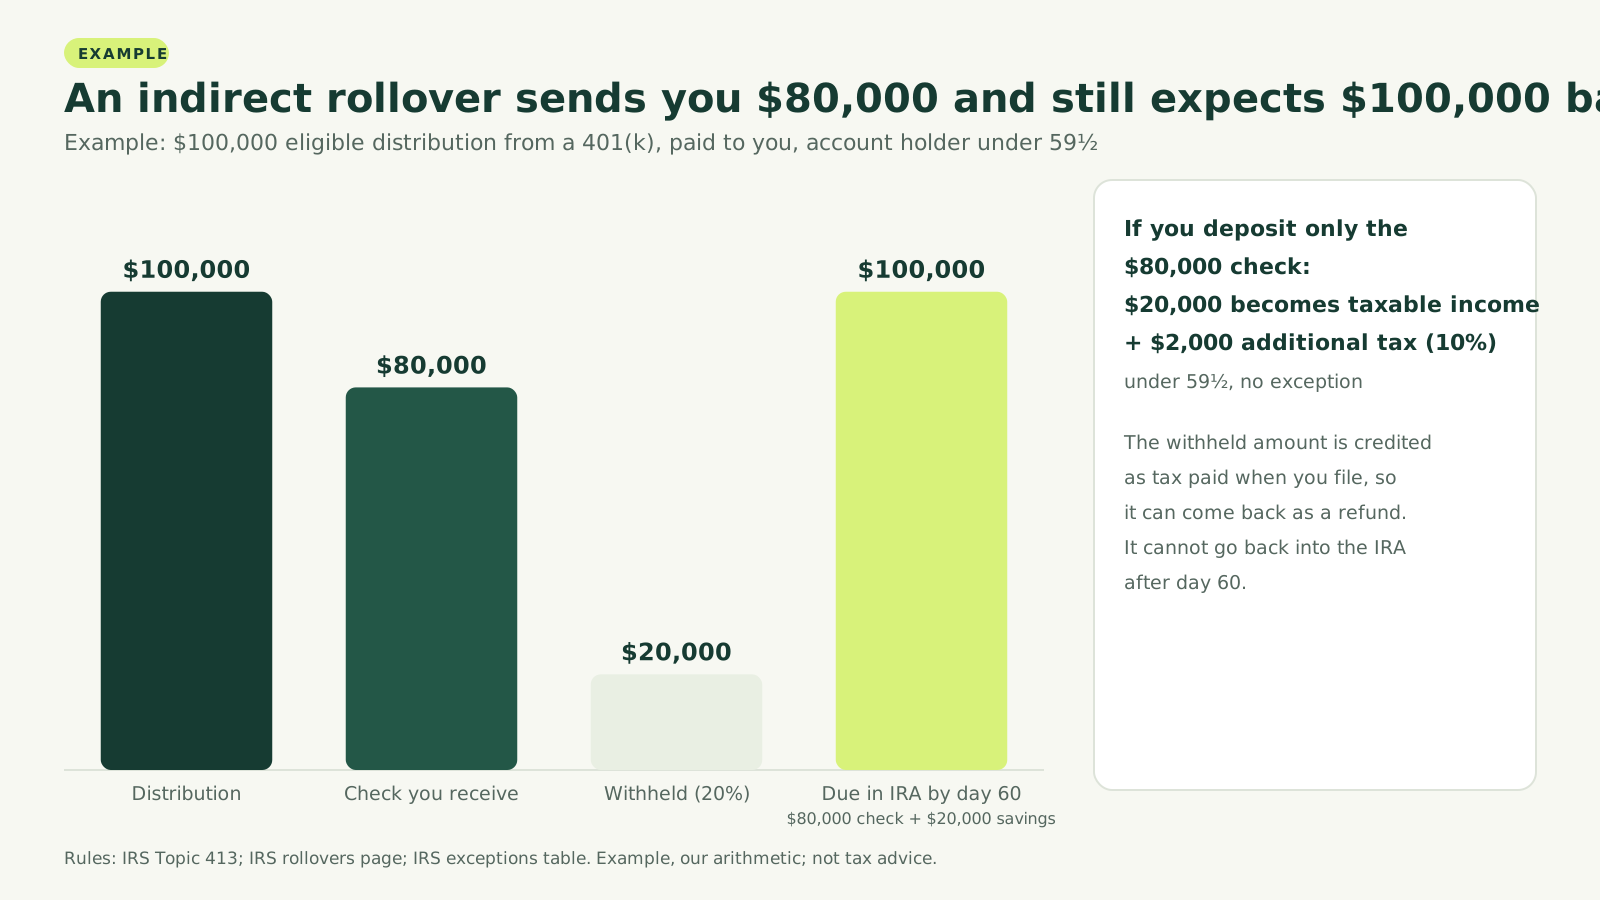
Example (hypothetical, account holder aged 50, no exception to the 10% additional tax):
| Step | Amount |
|---|---|
| Eligible distribution from the 401(k) | $100,000 |
| Withheld by the plan (20%) | $20,000 |
| Check you receive | $80,000 |
| Must reach the IRA by day 60 to keep it all tax-free | $100,000 |
| Of which, from your own savings | $20,000 |
| If you deposit only $80,000: added to taxable income | $20,000 |
| If you deposit only $80,000: 10% additional tax | $2,000 |
In both versions the $20,000 withheld counts as tax paid when you file. The IRS's own example works the same way with $10,000: roll over all of it and the withholding comes back to you through the return; roll over only the check and the shortfall is income, with the 10% on top.1 The second path also takes $20,000 permanently out of the tax-deferred account.
We see no reason to pick the indirect route on purpose for a 401(k) payout. People usually land in it by accident: the old provider could not set up the transfer and mailed a check payable to the participant, or a form box went unticked. Read the payee line before you accept anything.
Missed the 60 days
Missing the deadline is not always final. The IRS recognizes three routes.4
- Automatic waiver. The financial institution received the money in time, you followed its deposit instructions, and only its error kept the deposit from happening. The deposit must land within one year from the start of the 60-day period.4
- Self-certification. You give the receiving institution a written certification, using the model letter, that one of the listed reasons stopped you. The reasons include an error by either financial institution, a check that was misplaced and never cashed, a postal error, serious illness or a death in the family, severe damage to your home, and a distribution sent to a state unclaimed property fund.5 You must deposit as soon as practicable once the problem ends; within 30 days counts.5
- Private letter ruling. You apply to the IRS and pay a user fee.4
Self-certification has limits. It is not an IRS waiver: if the return is audited, the IRS can decide you did not qualify and assess tax and penalties.4 The receiving IRA provider also does not have to accept the late deposit.4 And it fixes only the deadline, not other defects such as a second IRA-to-IRA rollover within 12 months.5
That 12-month limit applies only between IRAs. Plan-to-IRA and plan-to-plan rollovers, and direct trustee-to-trustee transfers, do not count toward it.1
What rolling into an IRA changes
The rollover itself is not taxed when pre-tax money goes to a pre-tax account.2 The rules that follow the money do change.
The Rule of 55. Distributions from an employer plan escape the 10% additional tax if you leave that employer during or after the calendar year you turn 55 (50 for qualified public safety employees). The exception does not apply to IRAs.6 FINRA lists this as one of the factors to weigh, alongside fees and investment choice.10 If the plan is part of how you bridge to 59½, keep at least the amount you will need there.
Two plan rules decide whether this works in practice, and both are worth getting in writing before your last day. First, does the plan allow partial withdrawals after you leave, or only a payout of the whole balance? With a full-payout-only plan you get one shot: the part you take as cash avoids the 10%, and the part you roll over loses the exception. Second, if you are thinking of rolling old 401(k)s into your current employer's plan before you leave so that more money sits under the exception, ask the administrator how rollover money is treated for distributions. That is a plan-specific answer, and a tax professional should confirm it. The other routes are covered in retirement money before 59½.
After-tax contributions. A distribution normally carries a pro rata share of pre-tax and after-tax money. If you take the whole balance and send it to several places at once, Notice 2014-54 lets you direct all pre-tax amounts (including earnings on after-tax contributions) to a traditional IRA or plan, and the after-tax contributions to a Roth IRA, untaxed.78 A partial distribution of only the after-tax part is not allowed.7 The mega backdoor Roth guide covers how that after-tax money builds up.
Company stock. If the plan holds employer shares that have grown a lot, distribution rules for net unrealized appreciation generally leave the gain untaxed until you sell the shares, and then as a capital gain rather than ordinary income.910 Rolled into an IRA, the shares lose that treatment.10 This is a "stop and get help" item, not a do-it-yourself step.
A backdoor Roth IRA. The taxable share of a Roth conversion is figured using the December 31 value of all your traditional IRAs.12 Rolling a large pre-tax 401(k) into a traditional IRA in a year you also convert nondeductible contributions can make most of that conversion taxable. Rolling into the new employer's plan instead keeps the pre-tax money out of that calculation. Required minimum distributions. Distributions generally start at 73. Participants in a workplace plan can delay them from that plan until the year they retire, unless they own 5% of the business.11 An IRA has no such delay, so this matters if you keep working past 73 and roll old plans into the current one.
Questions to ask before you sign
FINRA's 2013 notice to brokers lists the factors a rollover recommendation should weigh.10 Turned into questions for the old plan, the new plan and any IRA provider:
- Investments. Which funds are available, and are they institutional share classes with low expense ratios?
- Fees. What does the plan charge for administration, and does the employer pay any of it? What will the IRA charge for the account and the funds?
- Services. Is there advice, planning help or a phone line you would actually use?
- Withdrawals and loans. Will you rely on the Rule of 55? Could you need a loan? FINRA notes it may be easier to borrow from a plan.10
- Creditor protection. FINRA lists it as a factor because plans and IRAs are treated differently. The answer depends on state law, so it is a question for a lawyer.10
- Required minimum distributions. Will you still work past 73 for an employer whose plan could hold this money?11
- Company stock. Do the shares have large gains that could qualify for NUA treatment?9
- Money types. Do you hold pre-tax, Roth and after-tax money, and where does each type go? The IRS rollover chart shows that Roth 401(k) money can go only to a Roth IRA or another Roth account.3
One more question belongs on the list. FINRA states plainly that an adviser who recommends an IRA rollover may earn commissions or an asset-based fee from it, while leaving the money in a plan "likely results in little or no compensation."10 Advice to roll over is not wrong for that reason. Ask how the person giving it is paid.
When not to roll over
- You left in or after the year you turned 55 and expect to withdraw before 59½. Keep the money you need for those years in the plan.6
- You hold highly appreciated employer stock and have not looked at NUA yet.9
- You make backdoor Roth IRA contributions and the only destination you have considered is a traditional IRA.12
- The old plan is cheaper than any IRA you would open, and you are satisfied with its funds. FINRA uses this exact case as an example of when a broader menu may not matter.10
If none of these apply, a direct rollover to a traditional IRA or to a new plan with good funds is the usual way to consolidate. The tax side of what you hold, pre-tax or Roth, is covered in Roth vs traditional, and the account basics are on the investing hub. For how this fits a retirement before 59½, see early retirement.
Sources
- Rollovers of retirement plan and IRA distributions, Internal Revenue Service. As of 2026-10-24.
- Topic no. 413, Rollovers from retirement plans, Internal Revenue Service. As of 2026-10-24.
- Rollover chart (allowable rollover transactions), Internal Revenue Service. As of 2026-10-24.
- Retirement plans FAQs relating to waivers of the 60-day rollover requirement, Internal Revenue Service. As of 2026-10-24.
- Revenue Procedure 2020-46 (self-certification for late rollovers), Internal Revenue Service. As of 2020-10-16.
- Retirement topics - Exceptions to tax on early distributions, Internal Revenue Service. As of 2026-10-24.
- Rollovers of after-tax contributions in retirement plans, Internal Revenue Service. As of 2026-10-24.
- Notice 2014-54: Guidance on Allocation of After-Tax Amounts to Rollovers, Internal Revenue Service. As of 2014-09-18.
- Topic no. 412, Lump-sum distributions (net unrealized appreciation), Internal Revenue Service. As of 2026-10-24.
- Regulatory Notice 13-45: Rollovers to Individual Retirement Accounts, FINRA. As of 2013-12-30.
- Retirement plan and IRA required minimum distributions FAQs, Internal Revenue Service. As of 2026-10-24.
- Instructions for Form 8606 (2025), Nondeductible IRAs, Internal Revenue Service. As of 2025-12-31.